Air conditioners are one of the most heavily financed purchases in the Indian appliance market, with roughly four in ten bought on some form of consumer finance, and in Kerala the financing conversation usually arrives at the worst possible moment: standing in a showroom in April, in a hot week, with a salesperson quoting a monthly figure instead of a price.
The monthly figure is the wrong number to shop on. It is designed to be comfortable, and comfort is not the same as cost. This guide sets out what to actually check before signing, and what to compare the offer against.
First, separate the three things being sold to you
A financed AC purchase is three separate transactions bundled into one signature.
- The equipment. The unit itself, at a price.
- The credit. Somebody lending you that price and being paid for it.
- The attachments. Extended warranty, insurance, protection plans, and sometimes accessories, added into the same instalment.
Each of these should be examined on its own. Bundled together, a weak deal on all three can look like a good deal on the monthly number.
The single most useful question
Ask this before anything else:
"What is the price if I pay in full today?"
Every subsequent judgement depends on knowing the cash price. If the seller cannot or will not quote one, or the cash price is suspiciously close to the financed total, you are not looking at free credit. You are looking at credit whose cost has been moved into the sticker.
No-cost EMI is a discount, not an absence of interest
Under a typical no-cost EMI scheme, the lender still charges interest. The brand pays the lender a subsidy, the retailer gives up some margin, and the buyer receives an upfront discount of roughly the interest amount, so the instalments add up to the sticker price. The credit is real, the interest is real, and somebody has paid it.
The Reserve Bank of India said as much when it looked at these schemes in 2013: the concept of zero percent interest "is non-existent", and where a manufacturer or dealer discount is available, the loan should be sanctioned on the discounted price rather than presented as interest-free credit.
What that means for you, practically:
- The discount you would have received for paying cash is what funded the "no cost".
- If a cash-payment discount is also available, you cannot usually have both. Compare them.
- Interest may still appear on your card statement and be reversed later as a credit, which is normal but worth watching.
- On a credit card EMI, 18% GST is charged on the interest component and is not reversed. Interest on an ordinary loan is exempt from GST, but card interest is specifically carved out of that exemption (entry 27 of GST Notification 12/2017-Central Tax (Rate)), so this cost belongs to card EMIs. On a cardless consumer durable loan, GST falls on the processing fee instead.
A short rule of thumb: if the cash price is the same as the amount being financed, no-cost EMI is a good deal. If paying cash would have earned you a discount, the EMI is costing you that discount.
You may also see a "triple zero" scheme advertised: zero interest, zero down payment, zero processing fee. It removes three of the costs in this guide. It does not remove the fourth, the cash discount you give up by taking it.
None of this makes no-cost EMI a bad product. It is often a genuinely good way to spread a necessary purchase. It just is not free, and treating it as free stops you from comparing it against the alternative.
What a no-cost EMI actually costs: a worked example
Take a ₹40,000 AC on a six-month no-cost credit card EMI. Card EMIs typically run at around 15% a year, so over six months the bank charges about ₹1,770 in interest, which the discount cancels. What it does not cancel:
Now set that against the money that stays in your account while you pay in instalments. The balance you would otherwise have spent falls from ₹40,000 to zero over six months, an average of about ₹23,300. In a sweep deposit at 6.5%:
So the two decisions come out close to even:
- No cash discount on offer: EMI costs about ₹670, the money left in the bank earns about ₹760. No-cost EMI is a reasonable way to keep your cash.
- A ₹2,000 cash discount on offer: paying cash saves roughly ₹2,000 + ₹670 − ₹760 ≈ ₹1,900. Pay cash.
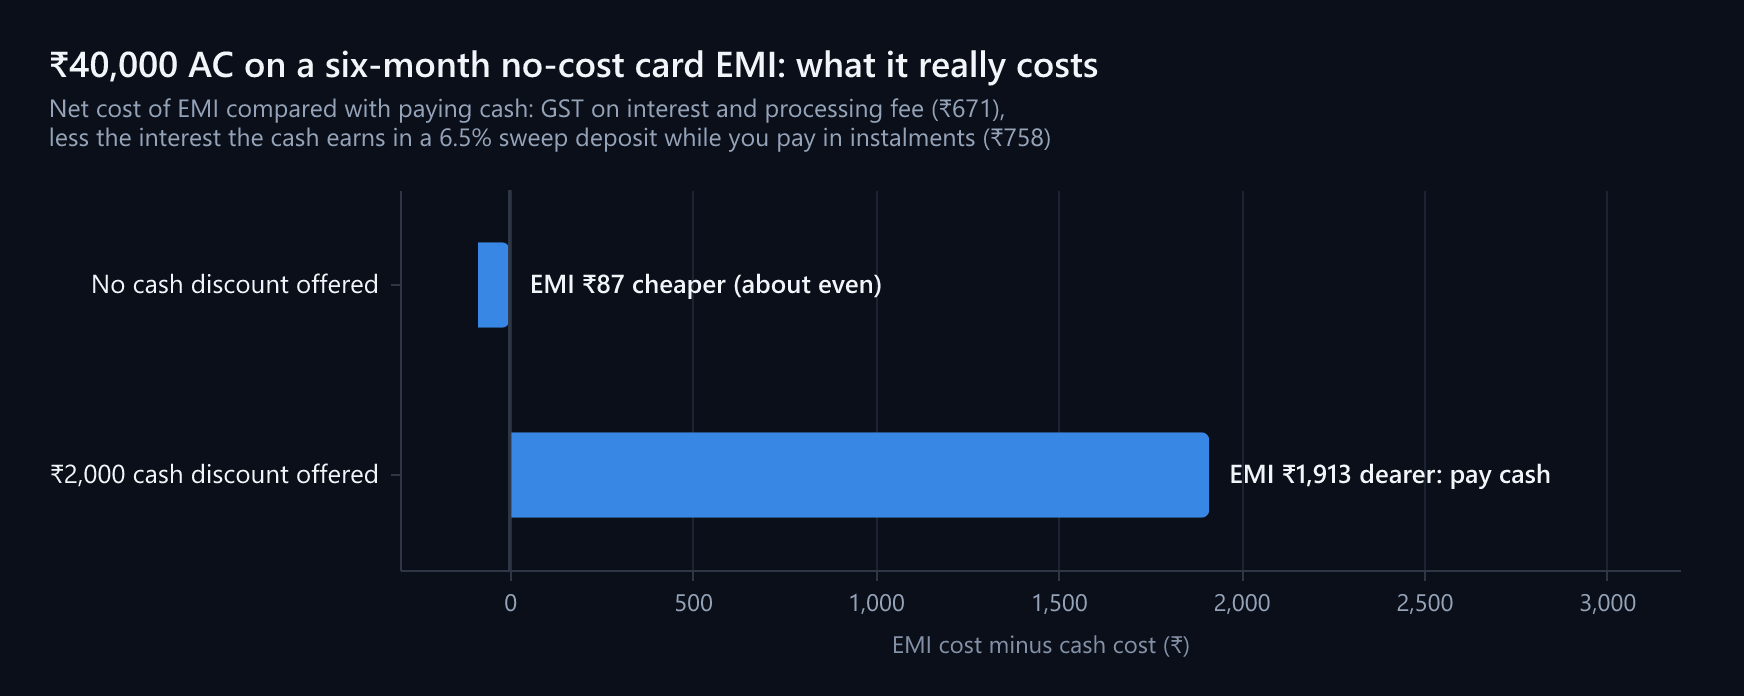
The interest rate, fee and deposit rate in your own case will differ. The structure of the answer does not: the cash discount decides it. Card and brand offers also change by season, and some instant bank discounts are offered only on card EMI, which can tip the result the other way. Ask for both totals before deciding.
The charges that are easy to miss
Ask for each of these in writing before you agree:
Processing or file charges. Commonly a few hundred rupees plus GST, often added to the first instalment rather than quoted upfront.
Advance EMI. Some consumer durable loan schemes collect instalments at the time of purchase. A "12-month" plan can be three instalments paid on the day and nine monthly ones after. Your effective tenure is shorter and your effective rate higher than the headline suggests.
Down payment. Separate from advance EMI, and separate again from the deposit some schemes ask for on higher-value systems.
Foreclosure and part-payment charges. If you intend to close early, ask what that costs and after how many instalments it is permitted. Some schemes do not allow it at all in the first few months.
Bounce and late payment charges. Worth knowing, because the amounts are usually much larger than people assume, and a missed instalment also reaches your credit record.
Credit limit blocking. A card EMI blocks your limit for the full purchase value, not the monthly instalment. If you are running close to your limit or expect another large expense, that matters.
The easiest way to see all of this at once is to ask for the Key Facts Statement. Since 1 October 2024, the RBI requires banks and NBFCs to give every retail borrower one before signing, in a standard format, showing the Annual Percentage Rate: the yearly cost of the loan with the interest and every fee folded in. A charge that is not in the Key Facts Statement cannot be collected later without your explicit consent. It does not cover credit card EMIs, so on a card, ask the bank for the interest, fee and GST in writing instead.
Card EMI, consumer durable loan, or personal loan
Credit card EMI is the simplest to arrange, is usually available instantly, and needs no fresh documentation. It consumes your card limit and the rate outside a no-cost scheme is often not competitive.
Consumer durable loans from a finance company are the most common route in appliance retail. The larger Kerala showrooms have lenders' representatives working inside the store, so the loan is approved at the counter with Aadhaar, PAN and a cancelled cheque, no credit card needed, on tenures from about three months to two years. They are quick, frequently carry the no-cost schemes, and require KYC at the point of sale. Read the schedule carefully, because this is where advance EMI, file charges and insurance add-ons most often appear.
Personal loans rarely make sense for a single split AC. They start to make sense for a whole-house or whole-property installation of several lakh rupees, where you are financing a project rather than an appliance, and where a lower rate over a longer tenure beats a retail scheme.
Business purchases are a separate conversation. Ask your accountant how the equipment should be invoiced and whether it qualifies for input tax credit before choosing between an outright purchase, a financed purchase, or a lease, because how the system is installed and whether it becomes part of the building can affect the answer. Get the tax position confirmed before the invoice is raised, not after.
Check what the finance offer actually covers
This is the gap that catches Kerala buyers most often, and it is the reason a financed purchase can end up costing more than a cash one even at zero interest.
Most schemes finance the product invoice only. That typically leaves out:
- installation charges beyond the standard scope
- copper beyond the included length
- the voltage stabiliser
- wall brackets, floor stands, or catwalk and service stands
- outdoor unit cages or guards
- electrical work: dedicated circuit, MCB, earthing
- any AMC or extended service plan
So the ₹45,000 unit is on a comfortable instalment and the ₹12,000 of things that make it work properly are due in cash, on installation day, at whatever price is quoted in the moment. That is exactly the pressure point where sites get scoped down and stabilisers get declared unnecessary. We set out what a complete package should contain in our guide to AC package deals versus box pricing.
Ask the seller directly: does the scheme cover the installed package or only the carton? If only the carton, budget the rest separately and do not let it be decided under time pressure.
The models on the scheme were chosen before you walked in
No-cost schemes are set model by model, each season, by the brand and the lender. That is why the advertising says "select models". The models on the scheme are the ones the brand is paying to move, and that is not the same list as the models best suited to your room.
In practice, the longest no-cost tenures and the smallest instalments in a showroom tend to sit on entry-level models and on brands whose authorised service network and spare-parts supply in Kerala is thinner than their advertising. The instalment ends in a year or two. The unit has to be serviced for ten. Before an easy instalment decides the brand for you, ask:
- where the nearest authorised service centre is, and whether it covers your district or only the city
- how quickly a compressor or PCB, the two expensive parts, can actually be sourced for that model
- how many years the brand keeps supplying parts after a model is discontinued
Schemes are also used to clear stock. BEE raised the ISEER threshold for every star band from 1 January 2026, so a unit labelled 5 star under the 2025 bands is a 4 star unit under the 2026 bands. Check the validity period printed on the star label: a current label shows a period beginning in 2026. An older label is not a reason to refuse the unit, but the price should reflect the rating it would carry today.
The number that outweighs the interest rate
The tempting move is to drop from an efficient unit to a cheaper, less efficient one so the instalment fits. Here is what that does, for a 1.5 ton split used as a bedroom unit most nights of the year, delivering about 6,000 kWh of cooling annually. Compare a 3 star unit at ISEER 4.4 with a 5 star unit at ISEER 5.7, both rated on the 2026 bands:
A household running an AC through the Kerala summer usually crosses 250 units a month, and from there KSEB bills every unit at a flat rate, roughly ₹7 to ₹8 a unit. At ₹7.60:
Suppose the 5 star unit costs ₹10,000 more. Financing that extra ₹10,000 over 24 months at 14% costs about ₹1,520 in interest. The electricity saved over the same 24 months is about ₹4,700, and the saving carries on for the rest of the unit's life.
Which produces an uncomfortable but useful conclusion: choosing a cheaper, less efficient unit to make the instalment smaller is usually the most expensive decision available. The monthly figure goes down and the total outflow goes up, because the electricity bill is also a monthly payment and it never ends.
Your own figures will differ, and our AC running cost guide shows how to work them out from any star label. Before you compare instalments, compare:
- rated ISEER and star rating, with the year of the label, at the tonnage you actually need
- your realistic running hours per day across the year
- your current tariff slab, because in Kerala the marginal unit is what an AC actually costs you, and an efficient unit can be the difference between staying under 250 units a month and crossing it
If you are unsure about the tonnage itself, get that settled first. An oversized unit financed at zero interest is still an oversized unit. Our guides on choosing the right AC tonnage and the most common AC buying mistakes in Kerala cover the sizing decision properly.
Extended warranty and protection plans
These are frequently added into the instalment, sometimes with only a passing mention. Before accepting one, check:
- what it covers that the manufacturer warranty does not, and from which year it starts
- whether compressor and PCB, the two expensive failures, are actually included
- who performs the service under the plan, and whether they are within reach of your location
- what invalidates it, and whether routine maintenance is a condition
- whether an AMC from a service provider who will actually attend is a better use of the same money
An extended warranty and an AMC are not the same product. The first is an insurance-shaped promise about parts. The second is a maintenance relationship that reduces the chance of needing them. We compare AMC structures in understanding AMC contracts.
Before you sign, and after
Before signing, get in writing:
- Cash price and financed total, side by side
- The Key Facts Statement with the Annual Percentage Rate; on a card EMI, the rate of interest or explicit confirmation of a no-cost scheme and who is bearing the interest
- All charges: processing, GST on interest, advance EMI, down payment
- Tenure, exact instalment amount, and first and last instalment dates
- Foreclosure terms and charges
- What the scheme covers, product only or installed package
- Every add-on listed separately, with a clear right to decline it
After the purchase, keep:
- the tax invoice in the correct name, especially for business purchases
- the loan agreement and the amortisation schedule
- the installation report and the warranty registration
- the closure letter or no-dues certificate at the end of the tenure, and a check that your credit record reflects the closure
That last one takes ten minutes and saves an argument two years later.
When paying cash is the better decision
If a genuine cash discount is on the table and you have the funds, take it. If the scheme requires an add-on you do not want, decline the scheme. If the instalment only fits by dropping to a unit that is too small or too inefficient for the room, the finance offer has quietly chosen your equipment for you, and that is the one outcome worth avoiding entirely.
The bottom line
Shop the price, not the instalment. Confirm what the scheme actually pays for. Budget the stabiliser, stands, electrical work and drainage separately if the finance does not cover them. And weigh the interest against the running cost, because for an air conditioner in Kerala, the electricity bill is the larger of the two.
Working out what an AC installation should actually cost? Hitech Refrigeration Services (HRS) provides itemised, market-rate quotations covering the unit, stabiliser, mounting, electrical readiness and drainage, so you can see the real total before deciding how to pay for it, and take that figure to whichever finance offer suits you. Authorised sales and service partner for Daikin and Carrier, authorised dealer for LG, Godrej, Toshiba and Midea, with engineers across all 14 districts. Request a quote or contact our team.